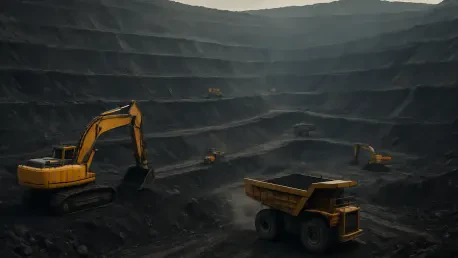
While coal mining enterprises are seeing theoretical profit margins skyrocket, their actual gains are significantly dampened by mandatory medium and long-term contractual delivery obligations. This paradox stands at the center of the recent surge in thermal coal prices, which saw the commodity surpass the psychologically and economically significant threshold of 1,000 yuan per ton in late 2026. On October 16, spot prices for 5,500 kcal thermal coal in the Bohai Rim region reached 1,025 yuan per ton, a staggering 47.27% increase since the beginning of the year. While such a spike might suggest a straightforward windfall for the mining sector and a crisis for energy consumers, the current economic landscape is defined by a sophisticated, multi-layered pricing mechanism that distributes financial pressure across various actors. This framework prevents a simple linear transmission of costs, ensuring that the 1,025-yuan price tag acts more as a market signal than a direct cost burden for the majority of participants. To understand the true impact of this milestone, one must look beyond the “thermometer” of spot prices and examine the structural shifts that have redefined the relationship between energy production and industrial consumption.
Market Indicators: The Reality of Contractual Obligations
The core subject of the current energy landscape is the socio-economic impact of high thermal coal prices on the industrial chain. This surge is not merely a supply-and-demand fluctuation but a rigorous test of the market-oriented reforms implemented in recent years. The central question remains how a nearly 50% increase in the raw material cost of energy is absorbed without causing systemic shocks. The answer lies in a four-tier pricing architecture that includes spot prices, long-term agreement prices, generation-side electricity rates, and final end-user costs. For most large-scale mining operations, the headline-grabbing spot price represents only a fraction of their total trade volume. The consensus among market analysts is that while the “1,000-yuan era” has returned, it serves as an indicator for the marginal market rather than a universal transaction price. This distinction is crucial for identifying who truly bears the financial weight of the price rally and how the system prevents localized volatility from turning into a broader economic crisis.
Regional authorities, particularly in major coal-producing hubs such as Shaanxi and Shanxi provinces, have maintained a stance of strict adherence to medium and long-term contracts throughout the 2026 calendar year. These contracts act as a fundamental stabilizing force, ensuring that a significant volume of coal is delivered to power plants at pre-negotiated prices that sit well below the current spot market rates. For mining enterprises, this means that while their official revenue reports might show growth, the actual magnitude of their profit expansion is capped by these security-focused obligations. From 2026 to 2027, the focus of regulatory oversight has shifted toward ensuring that coal delivery fulfillments remain above the 90% threshold, leaving only small surpluses available for sale at the elevated spot prices. Consequently, the high prices seen at the ports primarily affect smaller players or those seeking emergency supplies, while the backbone of the energy grid continues to operate on a much more stable and predictable cost basis.
Power Plant Resilience: Navigating the Three Buffer Layers
Historically, coal-fired power plants were the most vulnerable link in this industrial chain, often forced to operate at a loss when fuel costs outpaced regulated electricity rates. However, the operational environment in 2026 reflects a more resilient framework due to the successful implementation of three distinct “buffer layers.” The first layer is the aforementioned long-term coal contract system, which shields generators from the full brunt of spot market volatility. The second layer involves the liberalization of the power trading market, which allows for more flexible pricing in medium and long-term electricity contracts. This flexibility enables power plants to pass a portion of their fuel cost increases to industrial users who have the capacity to adjust their production schedules or pricing. By shifting away from fixed, rigid tariffs toward market-negotiated rates, the energy sector has created a more dynamic response to commodity price movements, preventing the “grid-locked” financial losses that characterized previous decades of high coal prices.
The third and most critical development in maintaining the solvency of power generators is the “capacity electricity price” mechanism. This policy ensures that thermal power plants are compensated not only for the electricity they generate but also for the essential stability and “peak-shaving” services they provide to the national grid. As the share of intermittent renewable energy sources continues to grow, the reliability of coal-fired units becomes increasingly valuable for preventing blackouts during periods of low wind or solar output. By decoupling a portion of revenue from actual generation and linking it to grid reliability, the government has provided a financial floor for these enterprises. This ensures that power plants remain operational and adequately funded even when the cost of coal peaks, as their role has transitioned from primary energy providers to the ultimate guarantors of system-wide energy security. This institutional shift has effectively mitigated the risk of fuel-driven bankruptcies within the midstream sector.
Industrial Economic Divide: Energy Intensity as a Survival Factor
For the broader manufacturing sector, the pressure of a 1,025-yuan coal price is not felt uniformly across the board. Instead, the impact is strictly determined by an individual enterprise’s energy intensity and its strategic procurement capabilities. For “asset-light” industries—those where electricity accounts for only a negligible fraction of total operating expenses—the coal price hike is largely an invisible event that does not fundamentally alter their competitive position. In contrast, “ordinary” manufacturing firms may experience a manageable uptick in their utility bills, though this is often delayed by the timing of their existing monthly or annual electricity contracts. This delay provides a vital window for businesses to optimize their energy usage or adjust their output prices, preventing immediate margin compression and allowing the broader economy to absorb the increased energy costs in a more gradual and orderly fashion.
The real pressure of the current price environment is concentrated in high-energy-consuming sectors such as electrolytic aluminum, ferroalloys, chemicals, and building materials. In these specific industries, electricity is not just a utility but a primary raw material input; even a fractional increase in the per-kWh price can erode an entire profit margin. Consequently, a trend of “cost-gap widening” has emerged within these sectors. Factories that have invested in advanced energy efficiency technologies or those with the bargaining power to lock in long-term electricity rates are developing a decisive competitive advantage. Conversely, operations that remain reliant on short-term market purchases of power or those with inefficient production lines are facing significant financial strain. This dynamic effectively uses market pricing as a filter, rewarding energy-efficient operations and high-value-added production while accelerating the phase-out of wasteful and low-leverage industrial capacity.
Consumer Safeguards: Maintaining Residential Price Insulation
A primary concern among the general public during periods of high commodity prices is the potential for a proportional increase in household utility bills. However, this fear remains largely unfounded due to the unique structure of the national energy market, which is designed to prioritize social stability. Residential electricity prices are intentionally insulated from the volatility of the coal spot market through government-mandated pricing and the strategic application of long-term contracts. The market-oriented reforms that have liberalized industrial rates were never intended to burden the average citizen. Instead, they were designed to redistribute the costs of energy transitions within the industrial and commercial sectors. As long as the current coal price spike is perceived as a cyclical fluctuation—driven by seasonal stockpiling or temporary supply constraints—the impact remains strictly contained within the professional industrial chain.
The insulation of the residential sector serves a dual purpose: it protects consumer purchasing power and ensures that the transition toward a more market-responsive energy grid does not trigger social unrest. Only a sustained, multi-year shift in the baseline of long-term coal contracts would eventually necessitate a reassessment of residential rates, and even then, such movements would be subject to rigorous regulatory oversight. In the current 2026 landscape, the state continues to use its influence to balance the books of power providers through non-residential tariff adjustments rather than passing costs to households. This strategic separation of the industrial and residential markets allows the economy to navigate high-energy-cost periods while maintaining the cost of living for the general population, effectively decoupling individual quality of life from the volatility of global commodity markets.
Future Considerations: Strategic Evolution of Energy Management
The move of thermal coal into the 1,000-yuan era signified a fundamental shift from a linear price transmission model to a complex web of benefit redistribution that favored system stability over individual profit. In the past, rising coal prices led to a predictable chain reaction of suffering power plants and a subsequent slowing of the broader economy. However, the implementation of capacity payments and liberalized trading mechanisms successfully transformed this dynamic. Stakeholders across the supply chain identified that the high spot price was not an insurmountable obstacle but a signal for more efficient resource allocation. By 2026, the burden of expensive energy was strategically directed toward high-emission industries, which encouraged a faster transition toward green energy alternatives and more sustainable production methods. This transition ensured that while individual commodity quotes remained high, the overall infrastructure of the energy grid was more resilient than in previous decades.
To maintain this balance, industrial operators moved toward deeper integration with renewable energy sources and invested heavily in on-site storage solutions to mitigate the impact of peak-hour pricing. Decision-makers within the manufacturing sector prioritized long-term electricity procurement strategies to avoid the volatility of the spot market, effectively mimicking the stability seen in the upstream coal sector. Regulatory bodies continued to refine the capacity price mechanism to ensure that the transition away from coal-dependence did not leave the grid vulnerable during peak demand periods. Ultimately, the 1,025-yuan milestone acted as a catalyst for a more mature energy market, where price transparency and contractual integrity became the primary tools for managing economic risk. Businesses that successfully adapted to this new paradigm by diversifying their energy portfolios and improving their energy efficiency profiles found themselves better positioned for long-term growth in an environment where energy costs are no longer fixed but strategically managed.