Christopher Hailstone stands at the forefront of the most significant energy pivot in over a century, bringing decades of boots-on-the-ground experience in utility management and grid security to the table. As an expert who has navigated the complexities of electricity delivery from the era of centralized coal plants to the current decentralized green revolution, he offers a unique perspective on the operational realities of the global transition. Today, the conversation is no longer about when the transition will happen, but how we are managing the massive scale of the shift that is already unfolding across the globe. We explore the multifaceted dynamics of this transformation, ranging from the historic moment renewables overtake coal to the surging energy demands of artificial intelligence and the critical role of battery storage in maintaining grid reliability. Throughout our discussion, we delve into the structural shifts in manufacturing, the divergence of international policy, and the strategic maneuvers businesses must take to remain competitive in a landscape where sustainability and profitability have finally become inseparable.
How does it feel to witness mid-year as renewable energy officially moves to eclipse coal as the primary source of global electricity generation, and what does this transition signify for the legacy of fossil fuels?
It is a profound moment to realize that we are finally ending coal’s century-long dominance of the global power mix. This shift isn’t just a symbolic victory for environmentalists; it is a fundamental restructuring of the world’s industrial foundation. In 2025, we saw record-breaking installations where solar and wind together exceeded 800 gigawatts in a single year, a scale that would have been completely dismissed as impossible just five years ago. Even as fossil fuels currently supply more than half of our electricity, the momentum is irreversible because solar photovoltaic capacity alone met more than a quarter of global energy demand growth last year. Seeing cumulative solar reaching approximately 2,800 gigawatts makes it the largest installed capacity of any generation technology, proving that the sun has become the new backbone of our energy security.
What are the primary economic and geopolitical forces that have turned renewable energy into the default choice for new capacity, and how are these factors influencing the way nations prioritize energy security?
The economics have shifted so decisively that more than 90% of new renewable projects are now cheaper to build than any fossil fuel alternative, making clean power the most rational financial decision for any developer. We are seeing countries move away from imported fossil fuels toward domestically generated power because recent geopolitical volatility has highlighted the danger of depending on foreign supply chains for energy. This push for energy security is being bolstered by tightening carbon regulations, such as the EU’s Carbon Border Adjustment Mechanism and new national carbon markets in China and Japan, which place a direct, unavoidable cost on emissions. Furthermore, the global green energy market, which was valued at approximately USD 129.09 billion in 2024, is now on a trajectory to reach USD 535.8 billion by 2034, driven by a compound annual growth rate of 15.3%. This massive influx of capital is reshaping how governments view their long-term industrial competitiveness on the global stage.
With battery storage being described as the fastest-growing power technology, what specific role do you see these systems playing in the grid as we move through this year and toward the massive 2036 capacity projections?
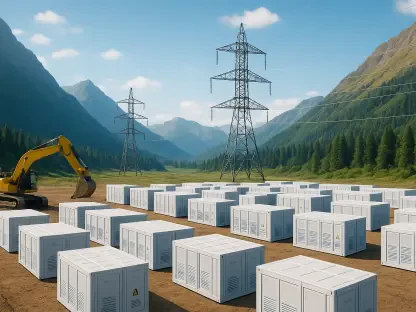
Battery energy storage systems, or BESS, are the vital bridge that allows us to manage the inherent intermittency of solar and wind power. Last year, global installations rose to 112 gigawatts, or 307 gigawatt-hours, and we are currently in the middle of a 41% jump that will see installations reach 158 gigawatts and 459 gigawatt-hours by the end of this year. Looking further ahead, the projection of reaching 2.9 terawatts of cumulative capacity by 2036 is what will truly allow us to phase out “peaker” plants that rely on gas or coal. In the United States alone, we are expecting to install close to 15 gigawatts of new BESS capacity this year, while countries like Germany and Australia are each adding about 5 gigawatts. This rapid scaling is essential because as we hit higher penetration levels—like Denmark, which already generates 70% of its electricity from wind and solar—the grid requires immense flexibility to prevent outages and manage surplus energy.
How is the sudden explosion of artificial intelligence and the proliferation of data centers fundamentally altering electricity demand patterns and forcing utilities to rethink their infrastructure timelines?
Artificial intelligence has become a massive engine of electricity consumption, driving global demand growth to roughly 3% last year, and we expect that annual growth to average 3.6% through 2030. This is nearly 50% faster than the growth we saw in the previous decade, primarily because hyperscalers and data center operators are scaling their workloads at an unprecedented pace. We are looking at a scenario where peak power demand could rise by as much as 26% by 2035, which creates an urgent need for utilities to bring new generation and transmission online much faster than traditional planning cycles allow. Interestingly, these tech giants are not just consumers; they are becoming the largest corporate buyers of renewable power, with power purchase agreements now accounting for about 30% of global renewable capacity expansion. This creates a unique synergy where the demand for AI is actually accelerating the deployment of the very green energy needed to power it.
The solar manufacturing sector is currently facing a structural oversupply that has caused significant financial strain for major players; how do you interpret this gap between production capacity and actual installation demand?
The solar industry has moved from a period of scarcity to a staggering structural oversupply where global polysilicon and module capacity are projected at roughly 2,034 gigawatts and 1,908 gigawatts respectively. When you compare that to a global installation demand of approximately 638 gigawatts for this year, you see a gap of more than 1.2 terawatts. This imbalance has real-world consequences, such as Chinese manufacturers reporting combined losses of USD 1.5 billion in just the first quarter of this year. While this oversupply is painful for manufacturers like LONGi Green Energy Technology, it is actually a boon for the transition as it keeps module prices low and encourages more rapid adoption in emerging markets. However, the industry must eventually find an equilibrium, or we risk losing the very innovation and production stability required for the next decade of growth.
In the face of rising renewable penetration, where do you see the most critical bottlenecks emerging within the global power grid, and what solutions are proving most effective in addressing them?
The constraint has moved from the ability to generate power to the ability to integrate it, with transmission and grid flexibility becoming the primary bottlenecks. We are seeing that simply adding solar panels isn’t enough if the grid can’t handle the load, which is why there is such a heavy focus right now on high-voltage direct current (HVDC) transmission and smart grid technologies. Beyond physical wires, we are seeing the rise of virtual power plants and long-duration storage as ways to manage the “duck curve” and avoid curtailment where energy is simply wasted because the grid cannot accept it. Companies like NextEra Energy and Iberdrola are leading the charge in integrating storage directly with generation to solve these issues at the source. This integrated approach not only improves the reliability of the system but also boosts the overall project returns by ensuring that every megawatt generated has a destination.
As heavy industries and transportation sectors look toward decarbonization, how is the integration of green hydrogen and carbon markets changing the financial landscape for industrial projects?
Capital is increasingly flowing toward integrated projects that combine renewable generation with green hydrogen production, especially for hard-to-abate sectors like steel and heavy manufacturing. While green hydrogen is still earlier in its cost-down curve compared to wind or solar, policy mechanisms like the EU’s Carbon Border Adjustment Mechanism are creating strong demand signals for low-carbon industrial output. We are also seeing the expansion of carbon and renewable energy certificate markets, which provide new, durable revenue streams for clean generation projects. In nations like Japan and China, new national carbon markets are forcing industrial players to evaluate their exposure to fossil-fuel-linked costs very carefully. This environment makes green hydrogen not just an environmental choice, but a strategic necessity for companies that want to avoid being hit by carbon taxes and remain competitive in global trade.
What is your forecast for the global green energy market as we look toward the next decade of expansion?
My forecast is that the global green energy market will continue its aggressive expansion to reach that USD 535.8 billion valuation by 2034, but the nature of the growth will shift from simple capacity addition to complex system integration. We are entering a phase where “smart” infrastructure—including AI-managed grids, massive battery arrays, and global hydrogen shipping lanes—will define the market leaders. I expect that the companies which treat this transition as a core strategic advantage, rather than a mere compliance obligation, will be the ones that capture the lion’s share of the 15.3% CAGR we are projecting. For our readers, my advice is to proactively diversify energy procurement through power purchase agreements and on-site storage now, rather than waiting for grid bottlenecks or carbon regulations to dictate your costs. The road ahead is clear: the organizations that understand the structural nature of this shift and act on it today will be the ones setting the pace for the global economy for years to come.