The sudden evaporation of the geopolitical tension that has gripped the energy sector for nearly a year became undeniable when traders watched the flickering digits of Brent crude finally tumble past the critical psychological barrier of ninety dollars. This decline was not merely a fluctuation in the charts; it represented a profound shift in market sentiment, signaling that the immense pressure on global supply chains might finally be finding a vent. For months, the international community remained braced for a disruption that many feared would redefine the economic landscape of the late decade, yet a series of calculated diplomatic signals from the highest levels of government provided the necessary cooling effect. This moment marks a pivot point where the “fear factor” that added a persistent premium to every barrel began to dissolve, replaced by a cautious curiosity about a world with more predictable energy costs.
The significance of this price drop extends far beyond the immediate savings at the pump or the lowered overhead for logistics giants. It serves as a real-time case study in how political narratives can influence global commodities more effectively than traditional supply-and-demand fundamentals. As the benchmark slipped below $90, it effectively challenged the assumption that conflict-driven inflation is an inescapable reality, suggesting instead that strategic restraint and clear communication can dismantle even the most stubborn price floors. This transition is essential for understanding the current economic trajectory, as it reveals the delicate balance between domestic political survival and international energy security.
The Moment the Risk Premium Evaporated
The global energy market recently witnessed a sharp pivot as Brent crude, the international benchmark, slipped below the threshold for the first time since the previous summer. This movement was largely precipitated by public comments from the White House that suggested a possible cooling of tensions in the long-standing confrontation between Washington and Tehran. By the close of the trading session, the price settled significantly lower, marking a clear departure from the triple-digit fears that dominated earlier forecasts. These price movements reflect the market’s high sensitivity to diplomatic rhetoric and the potential for a reduction in the “geopolitical risk premium” that has bolstered prices throughout the current cycle.
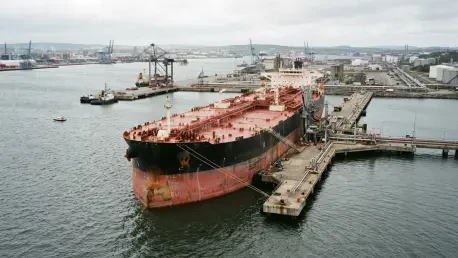
Beyond the numbers, the dip signifies a change in how traders perceive risk in the Middle East. For most of the year, any headline regarding the Strait of Hormuz or regional military posture would send prices upward, as the market baked in the worst-case scenario of a total supply shut-off. However, once the administration signaled a willingness to engage in dialogue, that protective layer of pricing began to peel away. The suddenness of the drop suggests that much of the previous price level was built on anticipation rather than actual shortages, proving that sentiment remains the most volatile component of the energy equation.
The High Stakes of Crude Volatility in 2024
Understanding this price drop requires looking back at a period defined by extreme swings, where Brent fluctuated from $60 to as high as $130 per barrel during the peaks of regional instability. This volatility was never just a number on a screen; it dictated the cost of living for billions of people, influencing everything from the price of transatlantic flights to the fundamental cost of heating homes in the Northern Hemisphere. As the conflict appeared to become a permanent fixture of the landscape, the global economy became increasingly desperate for a stabilization of energy costs to prevent a complete stalling of post-pandemic recovery efforts.
The economic fallout of this instability extended beyond raw crude prices into the realm of refining and logistics. Global consumers grappled with a shortage of refining capacity, which was exacerbated by secondary conflicts and infrastructure vulnerabilities in key production zones. These factors drove up the prices of essential refined products, including diesel and jet fuel, even when raw oil supplies appeared stable. The current descent below $90 provides a rare moment of relief, allowing industries that are heavily dependent on fuel to recalibrate their budgets for the 2026 to 2028 fiscal period without the constant threat of a price explosion.
Political Motivations and the Midterm Mandate
The primary driver behind the recent slump was the executive assertion that a resolution with regional adversaries could be reached fairly soon. This shift in tone is deeply rooted in domestic realities, as the administration acknowledged that high energy prices played a significant role in recent underwhelming election performances. To combat public fatigue and the rising cost of living, the government adopted a strategy of tactical restraint, creating a window for diplomacy that had been tightly shut for months. This pivot suggests that the dip below $90 was less about a change in physical oil supply and more about a calculated political move to ease the economic burden on the average consumer.
Domestic political pressures often force a re-evaluation of foreign policy priorities, and this case is no exception. The administration recognized that maintaining a hardline military stance was becoming a liability at the ballot box, where voters prioritized the price of gasoline over geopolitical posturing. By softening the rhetoric and inviting intermediaries to the table, the government successfully signaled to the markets that the era of “forever tension” might be pausing. This tactical de-escalation served as a release valve for the economy, proving that political survival and market stability are often two sides of the same coin.
Expert Perspectives: A Permanent Shift or a Temporary Lull?
Market analysts remain sharply divided on whether this price drop is the start of a long-term trend or a momentary lapse in an otherwise bullish market. Some strategists argue that the market is finally unwinding the risk premium as regional oil flows recover and diplomatic backchannels become more active. They point to signs that the regional powers are softening their stance regarding maritime control, suggesting that the downward pressure on prices is a logical reaction to a safer world. For these observers, the sub-$90 price point is a return to a “new normal” where diplomacy takes precedence over military engagement.
Conversely, skeptics warn that the fundamental disagreements—specifically regarding nuclear enrichment and territorial waters—are too deep for a quick fix. They suggest that the current price dip may be a narrow window of optimism before the reality of stalled negotiations or leadership transitions forces prices back upward. This camp believes that the underlying infrastructure risks remain as potent as ever and that the current decline is a fragile peace that could be shattered by a single misstep in the Gulf. The debate highlights the difficulty of forecasting energy prices in a world where a “two-week window” of diplomacy can be the difference between economic growth and a recession.
A Framework for Monitoring Future Energy Trends
To navigate this uncertain environment, observers established a set of indicators that dictated where the next major market move would go. They focused on tracking the “diplomatic window,” specifically looking for concrete progress on the transfer of enriched materials, which remained a non-starter for lasting peace. Investors also prioritized maritime security reports from the Strait of Hormuz, as any disruption there immediately reinjected the risk premium into the market. Furthermore, the shifts in refining capacity and the impact of secondary conflicts on diesel and jet fuel prices were monitored to ensure that raw crude stability was not undermined by a lack of finished products.
Market participants eventually realized that while the drop below ninety dollars provided temporary relief, long-term security required a more diversified approach to energy procurement. Governments and private entities alike moved toward strengthening their strategic reserves and investing in alternative energy corridors to reduce their sensitivity to single-point geopolitical failures. This period of lower prices allowed for a critical reassessment of energy dependencies, leading to the development of more resilient supply chain models. Ultimately, the lessons learned from this price fluctuation served as the foundation for a more stable economic framework that prioritized transparency and tactical diplomacy over the unpredictability of regional conflict.